- 0
- 1,122 word
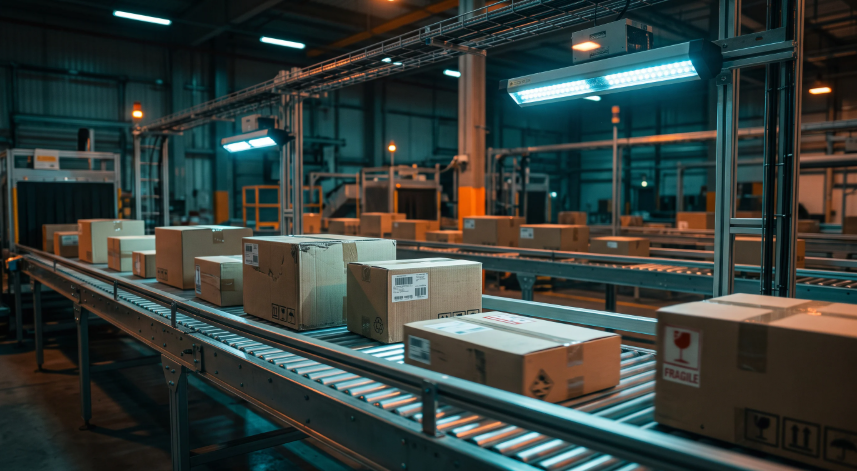
An online purchase takes seconds: a tap on a product page, a saved card autofilled, a confirmation email before the browser tab closes. Nothing on the screen shows the conveyor belts, pallet racks, and delivery vehicles behind the order.
E-commerce, as commonly discussed, is an interface story of conversion rates, ad creative, funnel design, and app onboarding. E-commerce, as actually operated, is a physical business of warehouses and delivery routes that has to meet its delivery commitments on schedule. Both layers matter, and only one of them is easy to copy. Outcomes depend heavily on the second.
Why the Front End Gets the Attention
The industry’s focus on the front end has a logic. Front-end levers move quickly: a sharper headline can lift a campaign within a week, and a shorter form can lift a checkout within a day. Feedback arrives fast, so attention pools where the feedback is, and the physical layer surfaces in public discussion as a line item, a shipping cost or fulfillment expense to negotiate down.
An order carries a deadline. The instant the confirmation email sends, a retailer has committed to finding an item inside a building somewhere, packing it, handing it to a carrier, and moving it to a doorstep before the window implied by the website closes. Every step can fail: stock can be absent while the site claims otherwise, an item can be picked wrong or damaged in transit, and a delivery can land late enough that the customer has already bought the thing elsewhere. Shoppers judge the retailer on the whole chain, and a parcel that arrives four days late with a crushed corner ends up in the reviews.
Storefronts replicate in weeks, because frameworks make competent front ends nearly free, design patterns are public, and a competitor’s checkout can be studied screen by screen on any phone. A fulfillment network is acreage leased in specific places, automation installed at capital cost, routing software tuned against years of delivery data, and labor hired in tight industrial markets, and none of that compresses into a quarter. The largest marketplace operators spent decades building their footprints, and rivals with ample cash found that money couldn’t substitute for time, because the binding constraint was the calendar.
Scaling behaves differently as well. A storefront absorbs a million simultaneous visitors at barely more cost than ten thousand, while a fulfillment operation scales in steps and with lag: doubled order volume eventually demands more shifts and more buildings, each consuming months of capital that cannot be recovered if demand fades. The holiday peak makes the contrast concrete, because the website rides out a Black Friday surge without visible strain while the warehouse absorbs it in overtime and error rates. The customer feels it in a delivery that slips from Friday to Tuesday.
Accounting conventions reinforce the neglect. Warehousing and delivery costs sit in operating expenses beside rent and utilities, which invites managers to treat a capability as overhead. Standard reporting shows fulfillment costs but not fulfillment earnings, so a retailer that starves the physical layer to protect quarterly margins defers costs onto the service failures that follow.
Last-Mile Delivery Economics
Long-haul freight amortizes well. One driver and one trailer carry tens of thousands of parcels, so dividing the journey across the cargo leaves almost nothing per unit, and sortation hubs extend the saving by pushing parcels through automation at a pace no human could match. Over long distances, scale keeps unit costs low.
A delivery route works differently. It is measured in stops rather than kilometers, and stops are bounded by parking, staircases, gate intercoms, and the walk from curb to door, so each drop takes a fixed quantity of driver time paid at an hourly wage whether the route is full or empty. The final leg of a shipment absorbs a disproportionate share of its delivery cost, and the number that governs it is delivery density: the drops a driver completes per hour. Density sets the labor cost per parcel, which is why identical delivery models are profitable in one city and unprofitable in another, and nothing about the retailer or the brand changes it.
Failed first attempts add a second cost. When nobody answers, the parcel returns to the depot, re-enters sortation, and consumes another driver-day on the next run, and a repeat attempt can exceed the shipping revenue on the parcel itself. The support tickets and refunds that follow land far from the operational cause, much as a mis-picked item in one warehouse suppresses sales in every market the review sites reach.
The main countermeasures work by raising density. Out-of-home delivery aggregates stops at pickup points and locker banks, replacing eighty doorsteps with one parking maneuver and eliminating the failed-attempt problem by letting the parcel wait for collection, though lockers carry fixed costs and pay only at high utilization. Hyperlocal fulfillment works from the opposite end by placing inventory inside the neighborhoods it serves, which makes routes dense by geography and pays for it in expensive urban space and stock fragmented across small sites. Quick commerce extended the model to ten-minute promises and hit its limit: density builds street by street, and capital cannot buy it in bulk.
How the Awards Program Classifies Logistics
That economics is the background against which an awards program’s classification becomes informative. The ECDMA Global Awards drew 538 nominations in the 2026 season, according to the program’s published materials, and its category groups include Logistics & Infrastructure, business achievement, marketing and strategy, agencies, technology solutions, and workplace culture. Judging runs May 1 to 30, and winners are published May 31, 2026.
The logistics group follows the same published mechanics as the marketing categories. Judges score independently against published per-category frameworks, rating each criterion from 1 to 10, with weights that sum to 100 percent and a final score on a 0 to 100 scale. A category produces one winner or no winner, and the bar is set in advance: a final score of at least 80 out of 100, plus at least 8 out of 10 on the criterion with the highest weight. Judges must disclose conflicts of interest and recuse, and scores remain confidential until official publication.
Against that economics, the classification matters. Marketing campaigns keep their own groups in the program, and the visible layer will always dominate conference keynotes. Infrastructure now gets judged by the same published bar, which puts the two layers in a single frame: the campaign that generates the order and the network that fulfills it. Operators who spent years building infrastructure that gets little keynote attention now have a place to score that work against published criteria instead of summarizing it as a cost line.
With this group, the program’s published 80-out-of-100 bar measures the fulfillment layer under the same standard applied to marketing.
Author

fraz.ashraf@gmail.com
Related Posts
A Comprehensive Guide to Concrete Installation for Durable, Reliable, and Long-Lasting Surfaces
- 0
- 2,776 words
Concrete is one of the most widely used materials in modern construction because of its strength, versatility, and ability to withstand everyday...
Read out all
Remote Workers Type All Day: How to Win Back the Hours Lost to Messages and Docs
- 0
- 1,398 word
Remote work was supposed to free up time. No commute, fewer hallway interruptions, more room for deep work. Instead, a lot of...
Read out all
Tips for a Smooth Window Installation Process
- 0
- 709 words
Installing new windows in a home helps enhance the exterior appearance, and it’s a practical upgrade. Modernizing your windows can also improve...
Read out all
Turning a Spare Room Into a Useful Space Starts With the Window
- 0
- 694 words
A spare room can become the most neglected space in a home. Furniture arrives without a clear purpose, boxes accumulate, and the...
Read out all
How Digital Marketing Can Help Colleges Reach More Prospective Students
- 0
- 834 words
For colleges and universities, getting students isnt just about decent courses, and modern facilities, etc. Applicants really want to know what the...
Read out all
How Food Businesses Can Reduce Risk When Sourcing Garlic Internationally:
- 0
- 807 words
For food manufacturers, wholesale distributors, and commercial supermarket buyers, international produce procurement offers substantial economic advantages. Sourcing agricultural commodities across borders allows...
Read out all